CbCR reportingCountry-by-Country reports, from Excel to ACD XML
Fill in familiar Excel templates, let automated checks catch errors and omissions, and generate the XML report for the Luxembourg tax authority (ACD). As an option, we file it for you.
| Code | Jurisdiction | Checks |
|---|---|---|
| LU | Luxembourg | No errors |
| DE | Germany | No errors |
| FR | France | 1 error |
| US | United States | No errors |
Excel
Guided templates for tax teams
BEPS
OECD Country-by-Country standard
XML
Generated for the ACD
ACD
Optional filing by Fund XP
What the solution does for you
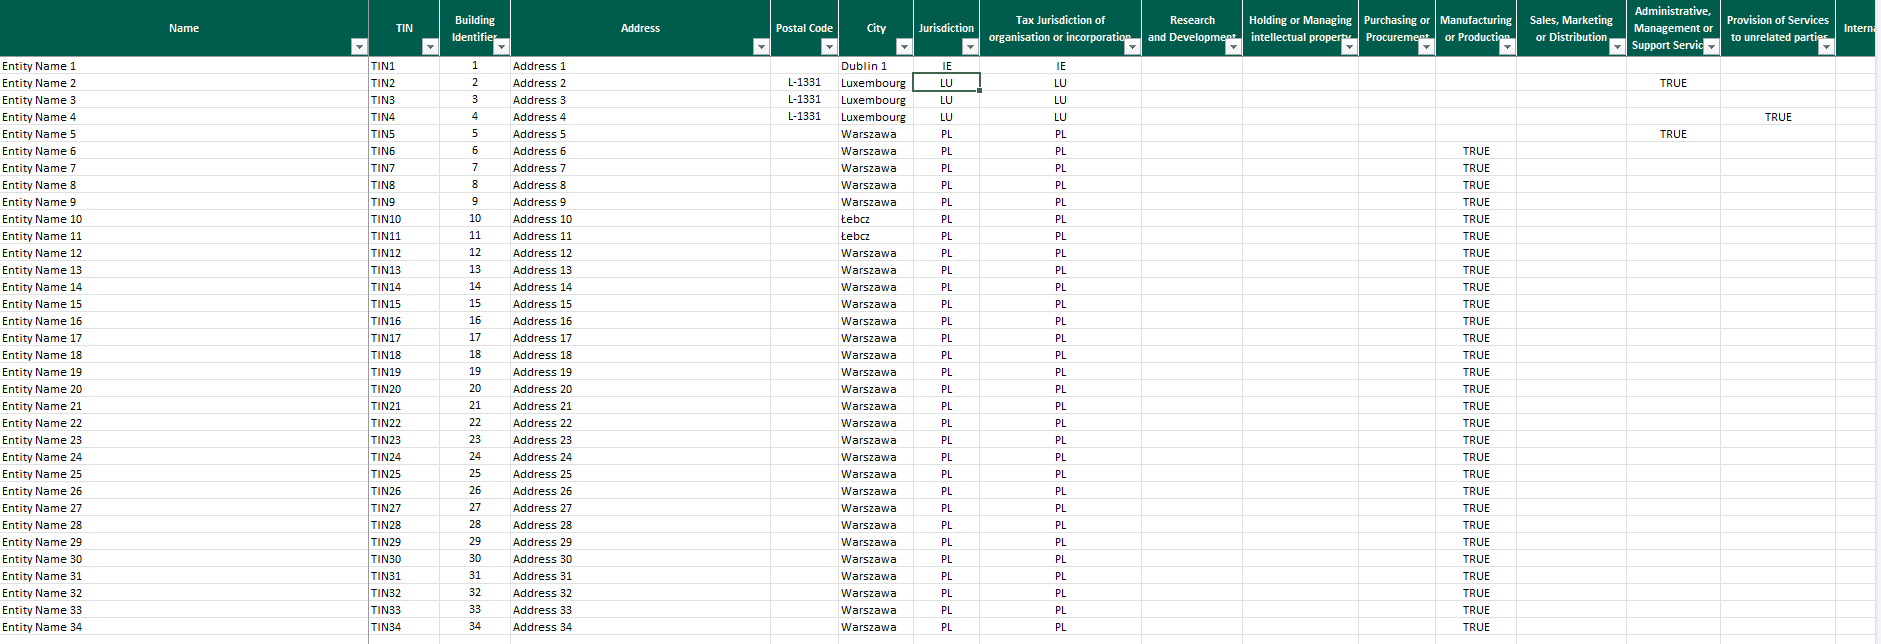
Familiar Excel templates
Financial and tax teams enter data directly in spreadsheets they know. The templates guide each step and limit errors.
Automated checks
Every report is built through automatic processes and validation checks, so errors and omissions are caught before the XML is created.
Always current
The solution follows the latest specifications, so your reports meet the regulatory standard in force.
Adapted to your group
Structures can be adjusted, supplementary information added and data formatted to your requirements.
On time
The automated production helps you meet the reporting deadlines.
Filing and support
Optional filing with the ACD, and a support team for template customisation and troubleshooting.

What a CbC report contains
CbCR, introduced by the OECD BEPS initiative, gives tax authorities a country-by-country view of where multinational groups earn their income, pay their taxes and carry out their activity. Most jurisdictions follow the OECD model template.
| Item | Content, per jurisdiction |
|---|---|
| Revenues | Total revenues generated in each jurisdiction |
| Profit or loss before income tax | Result before tax, per jurisdiction |
| Income tax paid | Income tax paid on a cash basis |
| Income tax accrued | Current-year tax accrued, which may include provisions for future tax liabilities |
| Stated capital | Amount of stated capital in each jurisdiction |
| Accumulated earnings | Net earnings retained in each jurisdiction |
| Number of employees | Full-time equivalent employees in each jurisdiction |
| Tangible assets | Tangible assets other than cash and cash equivalents |
| Business activities | Main business activities carried out in each jurisdiction |
Investment funds and management companies
The obligation can apply to the management company, to the investment funds, or to both. It depends on which entities must consolidate their accounts under US GAAP and form a multinational enterprise group.
- A group may exist if the management company has to consolidate the funds.
- Several groups may exist when the management company and the funds prepare separate financial statements.
- Each group files if it meets the USD 850 million revenue threshold and is not included in another group’s report.
From your data to the ACD
Fill in
Enter the group entities and the figures by jurisdiction in the Excel templates.
Check
Automated controls flag errors and omissions.
Generate
Create the XML report in the ACD format.
File
Submit it yourself, or let us file it with the ACD.
Frequently asked questions
What is CbCR reporting?
Country-by-Country Reporting is a requirement of the OECD Base Erosion and Profit Shifting (BEPS) initiative. Qualifying multinational enterprise groups report, for each jurisdiction where they operate, their revenues, profits, taxes and other indicators, so that tax authorities can compare the allocation of profits with economic activity.
What has to be reported?
For each jurisdiction: revenues, profit or loss before income tax, income tax paid and accrued, stated capital, accumulated earnings, number of employees, tangible assets other than cash, and the main business activities. Requirements can vary by jurisdiction, but most follow the OECD model template.
Does CbCR apply to the management company or to the investment fund?
It can apply to either, or both. It depends on which entities must consolidate their accounts under US GAAP (or would have to if they were listed) and form a multinational enterprise group. A group may exist if the management company has to consolidate the funds, or several groups may exist when the management company and the funds prepare separate financial statements, each of which may have to file if it meets the USD 850 million revenue threshold and is not included in another group’s report.
Which countries exchange CbC reports?
The OECD publishes the bilateral relationships in place for the automatic exchange of CbC reports between tax authorities.
Can Fund XP file the report?
Yes. As an option, Fund XP files the XML report with the Luxembourg tax authority (ACD).
Official documents
Other reporting solutions
Your next CbC report, checked before filing
Tell us about your group structure. We will show you the templates on your own data.